BEYOND THE PUMP! Why Uganda Must Fix the Weak Shilling, Boost Exports and Restore Confidence
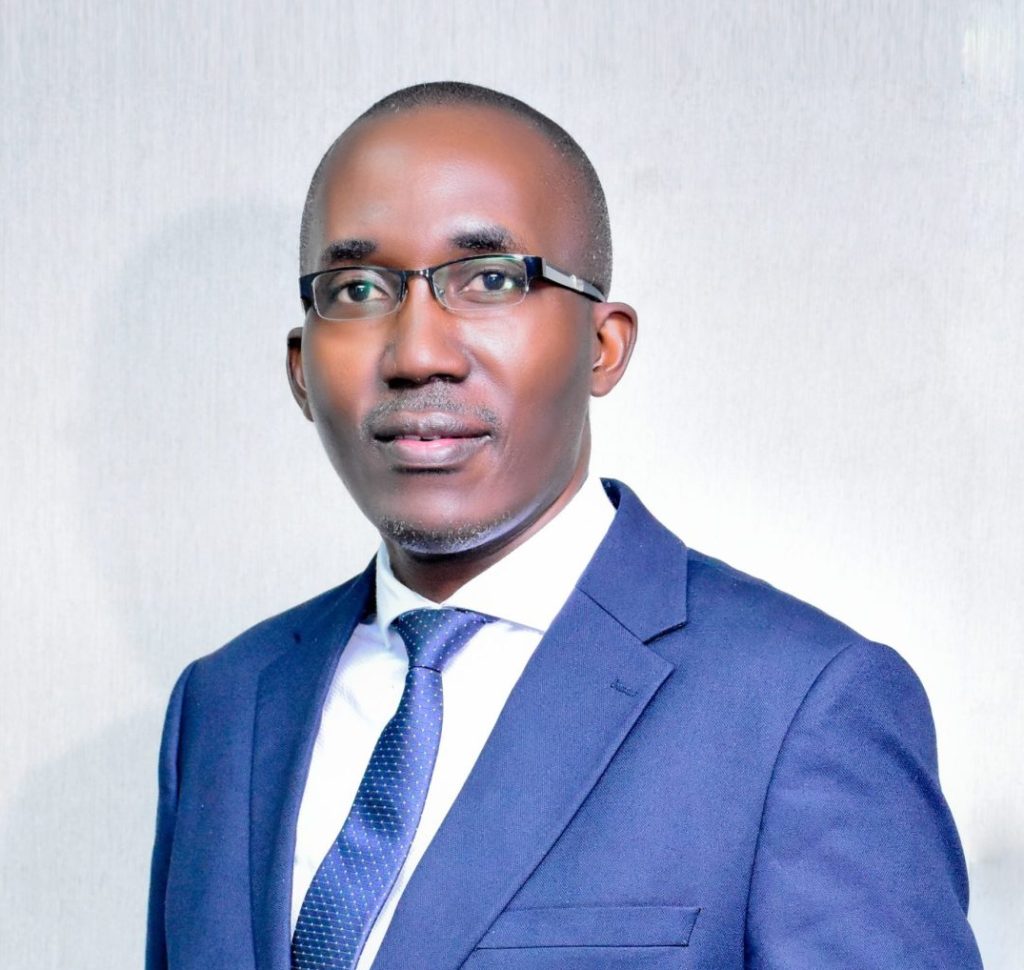
By Michael Jjingo, General Manager, Commercial Banking at Centenary Bank
By Michael Jjingo.
When the price of fuel rises, the pump is the only place where the problem becomes visible. Uganda’s rising fuel prices are telling us a much bigger economic story than what we see at the filling station. Between June and October, petrol has moved from about Shs.6,415 to Shs6,890 per litre, while diesel has risen from approximately Shs.6,510 to Shs7,190, an increase of nearly 11 percent in just four months. Adding to this is the tax increment of about Shs200 per litre, as the pressure becomes even more significant.
To this moment, the revealing number is the exchange rate: the Uganda shilling has moved from around Shs.3,634 in June to Shs4,140 in October, against the US dollar. In simple language, we are paying more for the same imported commodity because our currency has become weaker. And therein lies the real story, not the oil barrel price of $106.
Fuel is not mere fuel; it is an input into almost every productive activity. Diesel moves trucks, powers factories, supports construction, drives agricultural machinery and transports food from the village to the market. When diesel becomes more expensive, the farmer pays more to transport produce, the manufacturer pays more to run machinery, the trader pays more to move goods and ultimately the consumer pays more at the supermarket.
As economists put it, the fuel shock has a multiplier effect. As Milton Friedman reminded us, “Inflation is always and everywhere a monetary phenomenon,” but in an open economy like Uganda’s, imported inflation and exchange-rate movements can rapidly transmit external pressures into domestic prices.
Yet the most vulnerable participant in this chain remains the farmer. Our coffee farmer does not experience economics through narratives; he experiences it through the length of the dry spell, the price of fertiliser, the cost of transport and the price offered at the farm gate. A prolonged dry spell can reduce yields precisely when the cost of producing and transporting those yields is rising.
Less output, higher costs and uncertain prices- a perfect economic squeeze. If we genuinely want to transform agriculture, climate resilience cannot remain an environmental conversation; it must become an economic policy priority through irrigation, water harvesting, climate-smart farming, storage and value addition.
But there is another dimension to the equation that deserves greater attention: confidence. Uganda’s sovereignty legislation generated concerns among some development partners and foreign-funded organisations about the operating environment and the treatment of externally financed activities. Although the legislation was subsequently narrowed, perceptions matter in economics.
Capital is usually quiet and shy. Investors do not only look at returns; they look at predictability, policy consistency and institutional confidence. A country can be fully sovereign while remaining open, predictable and attractive to capital. Indeed, sovereignty without economic confidence can become an expensive luxury.
This is where Uganda must think beyond the immediate fuel-price debate. We need to ask a more fundamental question: how do we make the Ugandan economy less vulnerable to shocks that originate outside Uganda? The answer lies in increasing export earnings, deepening tourism, strengthening manufacturing, accelerating agro-processing, attracting quality foreign direct investment, expanding renewable energy, improving domestic production of strategic inputs and building sufficient strategic fuel reserves.
As Dambisa Moyo argues in her work on development, sustainable economic progress requires countries to think carefully about how they mobilise and deploy capital rather than simply depending on external financing.
Tourism provides another important piece of the puzzle. The Ebola outbreak created a significant disruption to international travel perceptions, with some tourists cancelling or postponing trips to Uganda. Although the country was eventually declared Ebola-free, the economic effects of such a shock do not disappear the day the medical emergency ends.
Well, Tourism is an invisible exporter: the visitor arrives with dollars, spends them locally and leaves the foreign exchange behind. When visitors stay away, the country loses not only hotel revenues but also foreign exchange, jobs, taxes, transport income and demand for local products. A tourist who does not arrive is, economically speaking, an export that never happened.
This is why Uganda’s response must be bigger than attempting to control the price displayed at the fuel station. We need an integrated economic response that protects the shilling, expands foreign-exchange earnings, supports productive sectors, rebuilds international confidence and reduces our dependence on imported energy and other strategic inputs. The debate should move from “How do we make fuel cheaper?” to “How do we make the entire economy cheaper and more productive?”
John Maynard Keynes highlighted that “When the facts change, I change my mind.” The facts before Uganda are changing rapidly. Global energy markets are volatile. Climate change is affecting agricultural productivity. The dollar is strengthening against the shilling. Development financing is becoming more cautious. Tourism is recovering from sensitivity to perceptions of safety (Kenya and DRC still with Ebola cases). At the same time, Uganda is pursuing an ambitious economic transformation agenda.
The answer, therefore, cannot be to fight every fire separately. Fuel is expensive. The dollar is expensive. Transport is expensive. Food is expensive. Capital is becoming more expensive. These are not five unrelated problems; they are different windows into the same economic house.
As Peter Drucker stated, effectiveness is not about doing more things; it is about doing the right things. Uganda therefore needs to focus relentlessly on the fundamentals: produce more, export more, attract more dollars, add more value locally, waste less and create greater confidence in the economy.
In conclusion, a dollar earned is often cheaper than a dollar borrowed. And that may be the most important lesson from the fuel price at the pump: Uganda does not simply need cheaper fuel. Uganda needs a cheaper, more productive and more resilient way of producing Uganda.
The writer is the General Manager of Commercial Banking at Centenary Bank.
GOT A HOT STORY? LET US KNOW!
Got breaking news, explosive secrets, or hard evidence?
Email us: redpeppertips@gmail.com
We accept tips, documents, videos, photos, and recordings—the more evidence you have, the better.
CONFIDENTIALITY IS OUR TOP PRIORITY. SOURCES ARE ALWAYS PROTECTED!
About Post Author