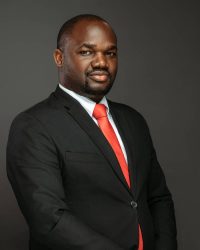
PETER M KAHINDI: New COVID-19 guidelines to Money Lenders, MDIs string-up requirement of arrears payment as precondition to qualify

The Uganda Microfinance Regulatory Authority(UMRA) has on April 20, 2020, overrode its advisory issued on the 8th of April 2020 and issued new Guidelines on credit management and loan restructuring during the COVID-19 pandemic under instrument No. G0001.
The guidelines shall be in force up to 12 months effective 1st April 2020, and are applicable to loans issued before April 2020 and loans that were not delinquent(in default) by March 2020.
The guidelines make it mandatory for all Microfinance Institutions and Money Lenders to grant a moratorium for loan repayments to borrowers that have been affected by the pandemic on a case by case basis with the institutions required to assess the ability of the borrowers to pay following the restructuring.
On the effects of the said requirement, the guidelines provide that the interest accrued during the moratorium can be capitalised and amortised during the loan period.
The guidelines suspend the requirement of payment of arrears as a precondition to qualify for these guidelines but give the Money lenders and Microfinance Institutions the right to capitalise the unpaid arrears after deducting any related interest or fees as part of the Loan facility restricting.
- CULTURE UNDER THREAT! Museveni Challenges Kingdoms to Save Languages, Traditional Family Values

- 2026 POLLS COURT BATTLE! NRM’s Jinja Deputy Mayor Nalumansi Loses Council Seat as Magoba Wins Election Petition
- 2026 POLLS COURT BATTLE! In Buhweju, High Court Expunges Mugumya’s Electronic Evidence in Atuhaire’s LCV Seat Election Petition
- 79-YEAR REVIVAL! CER Installs New Archbishop Tubamoi as Northern Uganda Church Marks Historic Milestone
- BABY DEATH CRISIS! MoH, UNICEF Probe Mystery Deaths After 48% of Baby Deaths Go Unexplained
- BANKING POWER MOVE! Housing Finance Bank Taps 20-Year Centenary Bank’s Veteran Moses Oroto to Drive Business Growth

Regarding fees chargeable due to the restructuring, UMRA directs that the same should be reasonable and justifiable by the institution, and in accordance with the institution’s approved policy.
It is incumbent on the borrowers to approach their lenders and vouch for the said loan restructuring on case by case instead of assuming that the Money Lenders and Microfinance Institutions shall initiate this process.
In conclusion, we appreciate the intervention that government agencies (UMRA) are making to ease loan repayments and make loan terms accommodative given these challenging times.
About Author: Peter Kahindi is Managing Partner at PACE Advocates in charge of Tax, Insurance, Finance & Banking. EMAIL: pkahindi@pace-advocates.com| Website: www.pace-advocates.com
About Post Author